Car Loan Interest Rates in India: What Determines the Rate You Get?
When you walk into a showroom to look at a new vehicle, you usually have a budget in mind, but the final cost often depends on the percentage the bank charges for the funds they provide. It is a bit like a personal score that follows you around, and most people do not realise how many different factors go into that one single number on the contract. You might see a very low rate on a billboard, but then find out that the actual offer you get is quite different once the lender looks at your paperwork. This happens more often than expected because a rate is not just a static number but a reflection of how the lender assesses the transaction’s risk over the next few years.
How Your History And The Market Shape The Offer
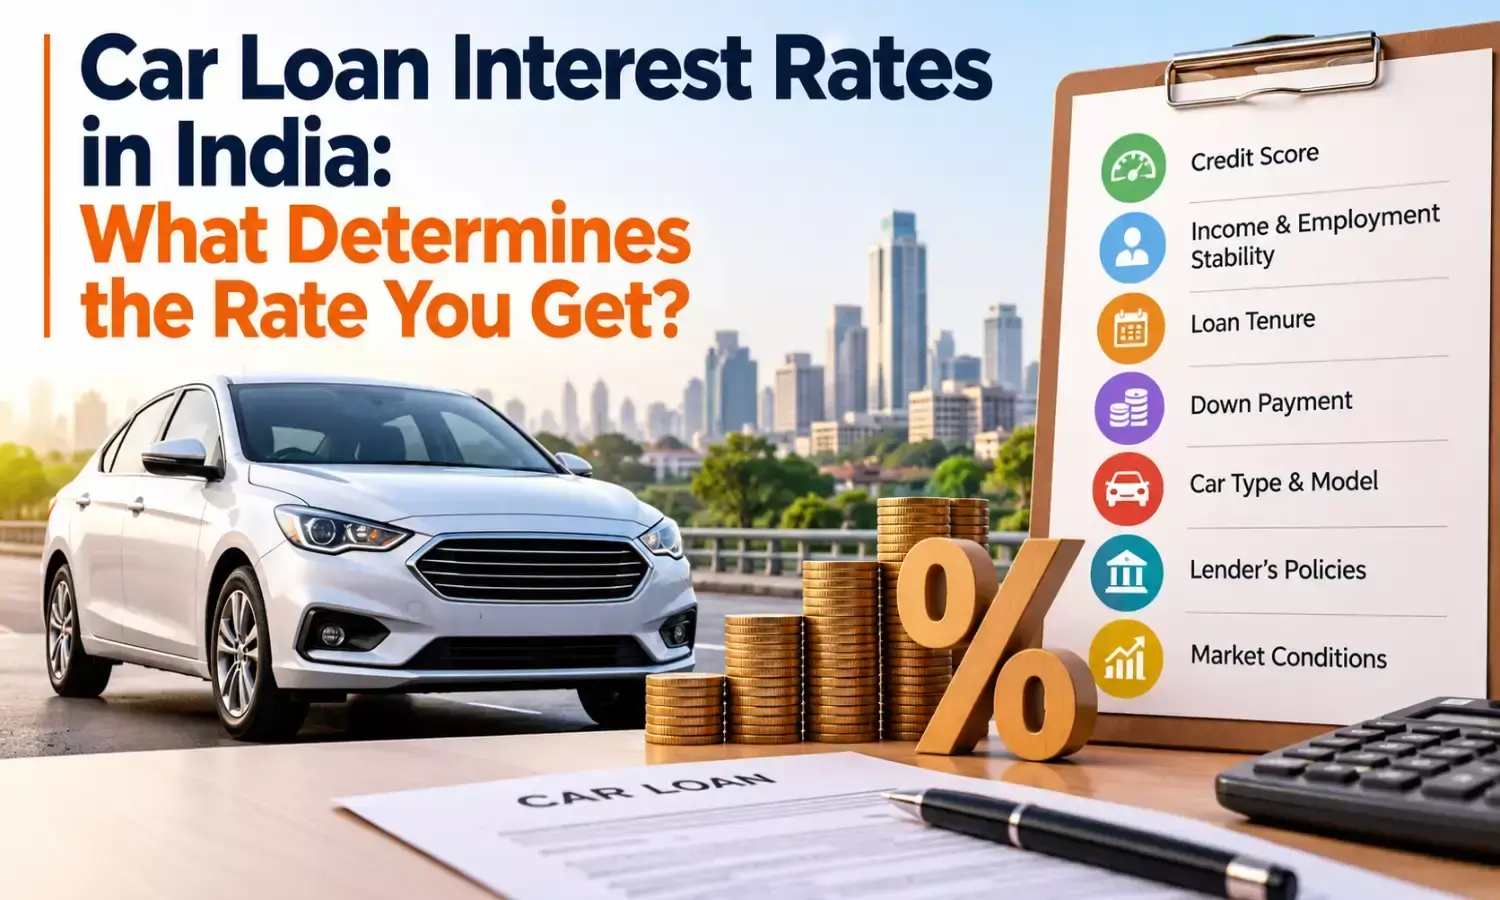
The most common factor that people talk about is the credit score, which acts as a summary of how you have handled your money in the past. If you have always paid your bills on time, the lender will feel more relaxed and might offer a lower rate because they trust you to keep up with payments. Beyond your own history, the central bank also plays a huge role because they set the base rates for the whole country, which trickle down to every local branch. When the economy is moving fast, and the central bank raises rates to keep things under control, you will see that every in the market becomes a little more expensive.
Mahindra Finance evaluates these market shifts alongside the profile of the person who wants to buy the vehicle to arrive at a fair rate. They look at your income stability, where you live and even what kind of work you do to see if you can assess overall creditworthiness and repayment capability. It is a practical way for them to ensure the debt does not become a burden for you later. Some people think that a higher income automatically means a lower rate, but that is not always the case if you already have a lot of other debts to pay off each month. Lenders like to see that you have plenty of room in your budget after all your expenses are met because it shows that you are a safe bet for a long-term commitment.
The Age Of The Vehicle And The Length Of The Plan
The type of vehicle you choose also makes a big difference in the math because a brand-new car usually comes with a lower rate than a used one. This is a realistic observation because a new car has a higher resale value if something goes wrong and the lender has to take it back. Used cars are seen as a bit riskier because their value depreciates faster, and they might have mechanical issues that make them less reliable as collateral for the debt. You also have to consider how long it takes to pay it back, because a longer plan might mean smaller monthly payments, but it often comes with higher over the total period.
A shorter plan means you pay less total interest, but your monthly bill will be much higher, which might squeeze your daily spending too much. It is a balance that requires some thought about how your life might change over the next five years. You might plan for a promotion, or you might have new family expenses, and all of these things should be part of the thought process when you pick the term. Small repetitions in your research can help here, as looking at the numbers from different angles can reveal the hidden costs people often overlook in the excitement of buying a new ride.
Finding a rate that works for your specific situation is about more than just finding the lowest number in the newspaper. It is about understanding how your own habits and the choice of the vehicle work together to create the final deal. Taking the time to clean up your old debts and saving for a slightly larger down payment can often lead to a much better offer than you might get otherwise.